Session Recap: What It Takes to Scale From Product to Profit
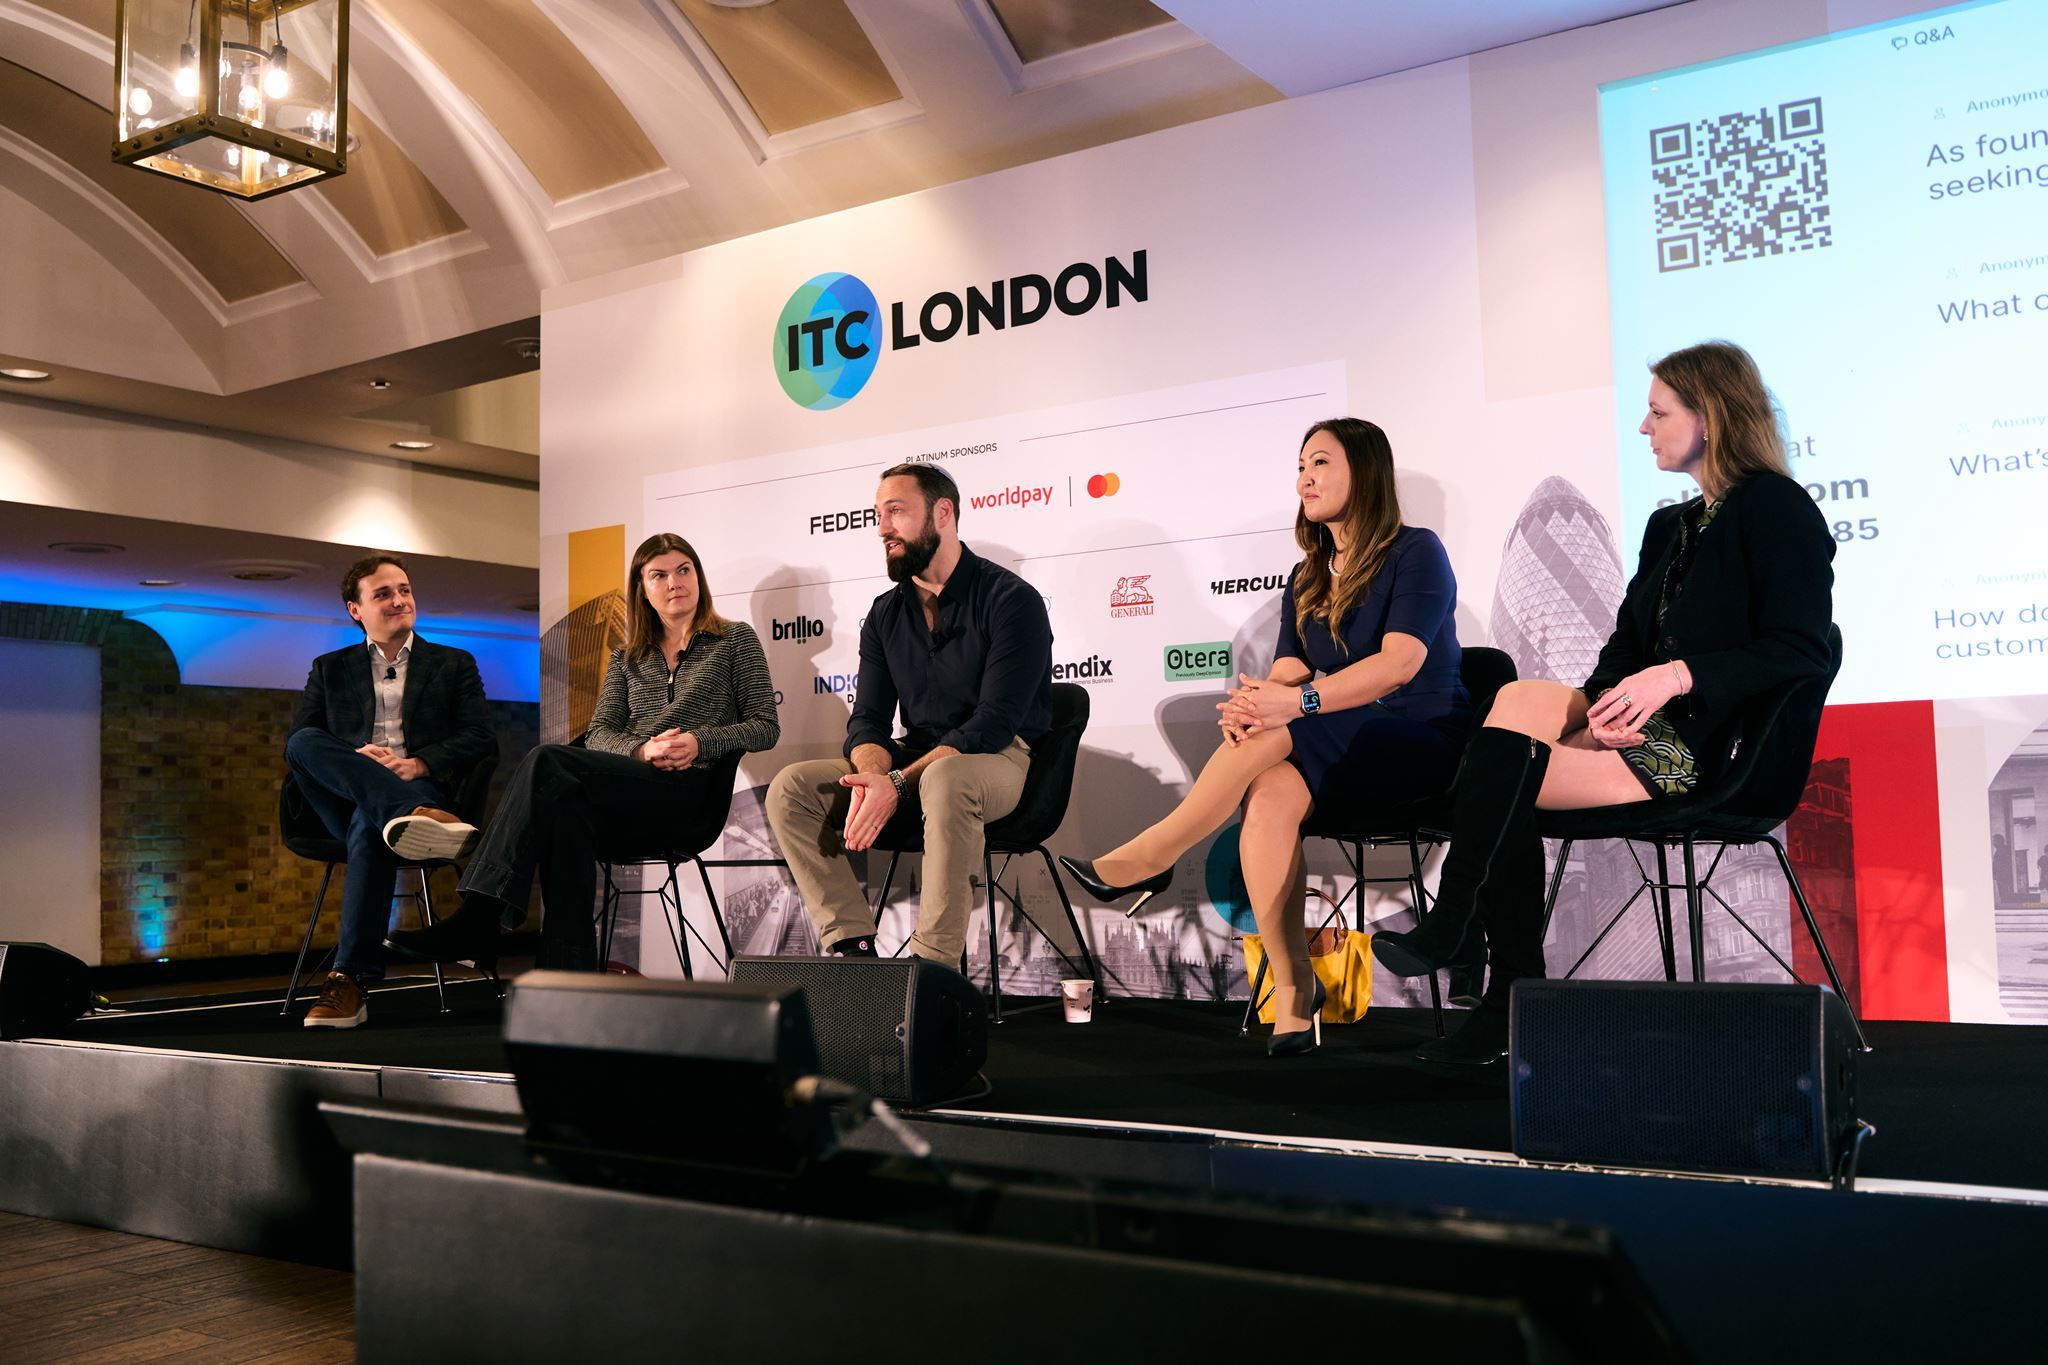
- Speakers:
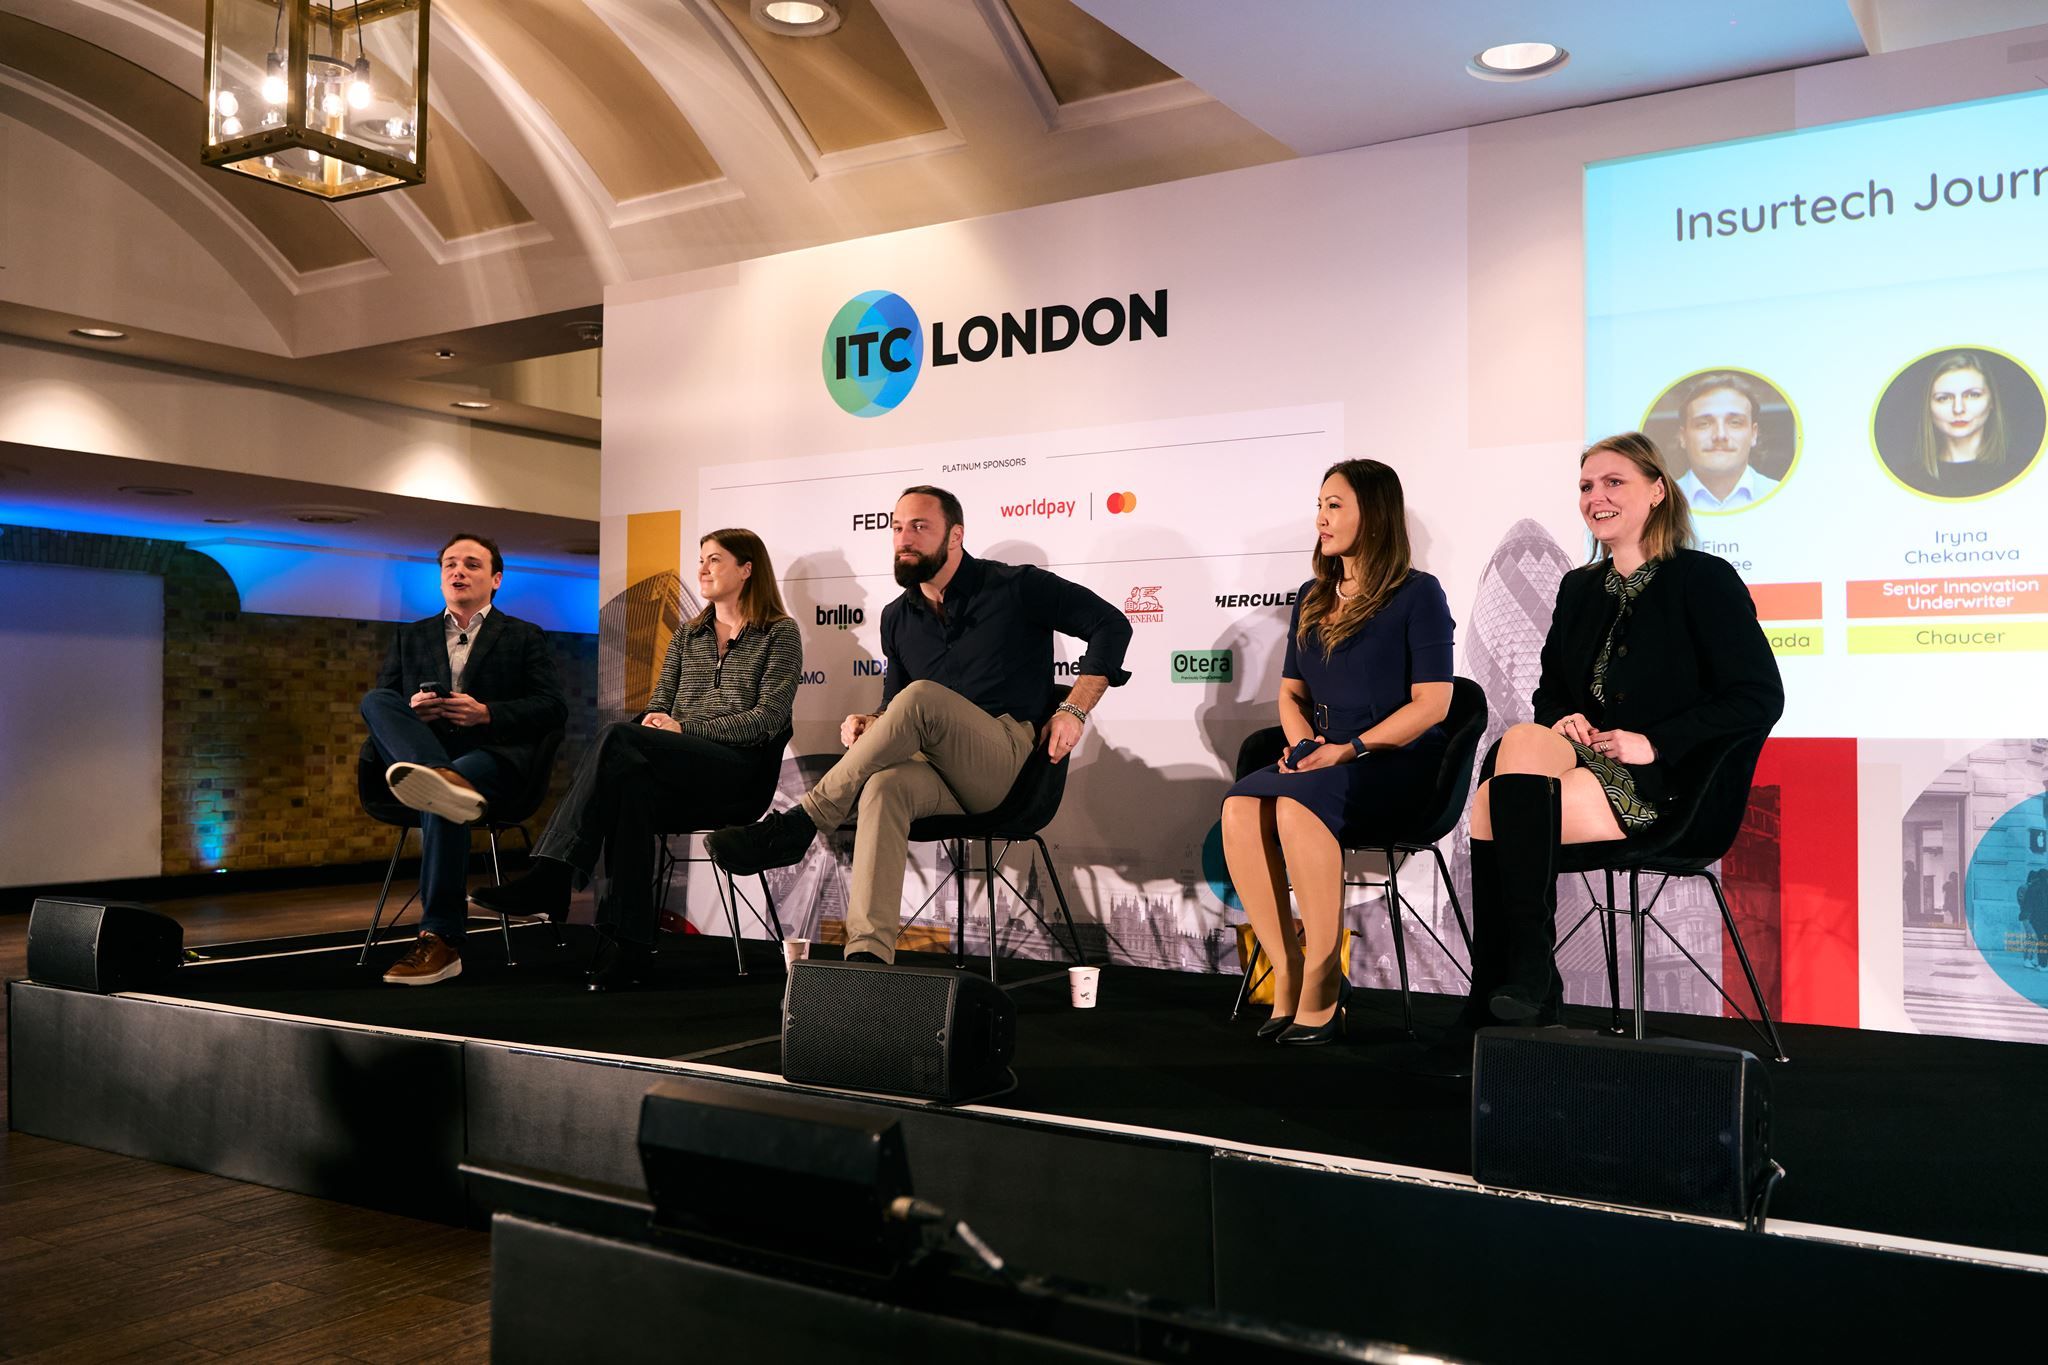
- Clare Dodd, UK General Manager, Empathy
- Sam Fromson, COO and Co-Founder, YuLife
- Janthana Kaenprakhamroy, CEO and Founder, Tapoly
- Iryna Chekanava, Senior Innovation Underwriter, Chaucer
- Finn Magee, CEO, Insurtech Canada (moderator)
- Session date: 27 January 2026
- Estimated read time: 12 minutes
Quick read summary
- Scaling a UK insurtech from product to profit takes longer, and depends more on distribution, than most founders plan for.
- Investors new to insurance are pulling back and MGAs are finding capacity harder to secure, so realism now wins backing.
- After years of hard market conditions, panellists see the advantage shifting from building technology to reaching customers.
- Plan carrier projects on 9 to 12 month timelines, treat every cap table decision as permanent, and build around insurers' constraints.
- Before your next carrier pitch, map several internal sponsors and cut any premium forecast you cannot defend.
Month nine of an insurer's procurement process is where many partnerships quietly stall. Clare Dodd, UK General Manager at Empathy, knows that stretch well: her company has completed more than 40 implementations with insurers and banks across North America, and it employs people whose job is to answer procurement questionnaires.
Iryna Chekanava, Senior Innovation Underwriter at Chaucer, sees the same process from the carrier's side and has yet to see a project, whether technology, capacity or a jointly built product, finish in under 9 to 12 months.
The panel at ITC London treated those timelines as the operating environment rather than an obstacle to complain about. Across four very different businesses, the argument was consistent. The insurtechs that reach profit are the ones that design their capital, their carrier relationships and their route to market around how insurance actually moves.
Why does scaling a UK insurtech take longer than founders expect?
Janthana Kaenprakhamroy, CEO and Founder of Tapoly, a digital MGA platform serving the gig economy, set out to build a distribution business. She quickly found she could not distribute without new products, and could not deliver those products without her own technology, so Tapoly became distributor, product designer and technology provider at once. The company then absorbed Brexit, a hard market and a pandemic that halted one of its product lines, and is now approaching its tenth anniversary.
Empathy took the opposite route and scaled fast. The company supports people through bereavement, from funeral planning and probate to the emotional aftermath, and in five years signed more than 40 partnerships with insurers and banks in the US and Canada, reaching over 50 million people. Dodd said the hardest part was building a consumer product good enough to sit on a phone beside social media apps, while making it acceptable to one of the most regulated industries in the world.
Creating a new category doubled the work. Empathy had to invent the insurer's value story alongside the user experience, and Dodd's regret is that it widened its lens too late. With hindsight, the company would have paired its product with a strategic ROI case for insurers sooner, and brought financial advisers into the model earlier.
What does a realistic carrier timeline look like?
Sam Fromson, COO and Co-Founder of YuLife, said global partnerships typically take nine months to a year simply to get going. YuLife covered that gap by serving employers and individuals directly, which produced early traction, while it built deeper carrier relationships in parallel. The lesson for founders is to fund the runway for the long cycle and find a faster source of proof alongside it.
Plan every carrier project, whether technology, capacity or a joint product, on a 9 to 12 month timeline, because Chaucer has yet to see one close faster.
How should founders choose insurtech investors and capacity partners?
YuLife now works with close to a million individuals across the UK, alongside some of the country's largest insurers, with offices in Japan and South Africa. Fromson credited investors who understood insurance complexity and backed the slow partnership cycle. He passed on a warning from one of the company's first advisers.
It's easier to get divorced than to get someone off your cap table.
Founders under pressure to raise can treat investor fit as secondary to valuation. Fromson's point is that a poorly matched backer stays in the business long after the money is spent, so the test is whether that investor will tolerate a year-long carrier cycle.
What makes a capacity provider walk away?
Chekanava described insurers as providers of risk capital, giving insurtechs and MGAs access to a balance sheet. Chaucer does not push partners to scale quickly, and treats an inflated total addressable market or an ambitious premium forecast as a red flag. Her team's working assumption is that a new product may write little premium in its first or second year.
She also described a shift in the funding market. Venture investors without an insurance background are drifting away because profit takes longer to arrive, and MGAs are struggling for capacity as a result. The upside, in her view, is a natural selection of founders who understand how regulated, slow and revenue-driven the business really is.
A premium forecast that assumes meaningful volume in year one or two reads to a capacity provider as a warning sign rather than ambition.
Why do insurtech partnerships with insurers stall, and what keeps them moving?
Dodd's first rule is values alignment from day one. If a carrier sees the product as a nice-to-have, it will not survive the procurement questionnaires and compliance reviews. Her second rule has become Empathy's operating principle.
You have to design for the conditions that exist rather than the ones that you want to exist.
In practice, that means Empathy staffs and schedules for procurement instead of trying to route around it. The company also offers versions of its implementation that need no code, because internal engineering time is one of the scarcest resources inside any insurer.
Chekanava agreed, arguing that insurance is no more complex than any large corporate, and that the best use of the waiting time is to find the people inside the carrier who are driven enough to champion the project.
What can insurers do to make partnerships easier?
 Fromson named continuity of people as the biggest problem. A sponsor leaves, a successor arrives with different priorities, and months of buy-in disappear. He urged carriers to build support across several stakeholders, ideally at board level, and urged founders to map who holds influence and maintain several relationships so one departure cannot sink a deal.
He also raised an uncomfortable asymmetry. A carrier can defer a decision for a year without anyone losing their job, while for the insurtech the deal is its lifeblood. Kaenprakhamroy added that insurers need dedicated teams staffed with people who understand both sides, ideally with founder and corporate experience.
Chaucer offers one working model. Its innovation team sits inside the underwriting division, and each partnership draws on a squad of pricing, claims and policy wording specialists who co-create products with insurtechs. Chekanava said few specialty insurers run a dedicated innovation function of this kind.
Why does customer adoption decide whether an insurtech survives?
YuLife's model depends on daily use. Fromson said the product is worthless if people stop opening it, which is why the company combines behavioural science with a design principle of giving users something they enjoy every day. He contrasted this with insurers' habit of launching technology that never engages anyone emotionally.
Regulation shapes that experience at every step. Kaenprakhamroy, who previously worked in internal audit at an investment bank, said Tapoly's consumer-facing business requires constant attention to compliance and legal procedure, and that her audit background made the transition familiar.
How do you serve vulnerable customers at scale?
Bereavement is Empathy's entire market, so Dodd builds vulnerable customer care into the product rather than bolting it on. She went further than personalised communication styles.
If you're going to really step up and help vulnerable individuals, you need to make it so that they don't even need to tell you that they are feeling vulnerable.
Empathy looks for signals such as the language people use and how often they return to particular parts of the platform. For carriers, the implication is that vulnerability detection can sit inside the claims journey itself, so support reaches people who would never ask for it.
Which insurance distribution strategy works for a scaling insurtech?
Tapoly tested almost every channel, from pay-per-click advertising to embedded partnerships. Kaenprakhamroy found her best channel was the company's own organic search, alongside partnerships nurtured over several years. Paid search produced spikes in volume, she said, but drained cash just as quickly.
Fromson made the case from the carrier side. Some insurers champion YuLife across their adviser and direct sales channels, and those are the partnerships that work. A value-added service buried at the back of a salesperson's mind is never mentioned, however good it is, so the product has to matter enough to the customer, the adviser and the insurer to earn a place in the sales conversation.
What should founders check before pitching an insurer?
The panel's experience condenses into a pre-pitch checklist.
- Tie the proposition to one of the carrier's core strategic goals, because a nice-to-have will not survive procurement (Dodd).
- Budget runway for a 9 to 12 month cycle, and find a faster source of traction to run alongside it (Chekanava, Fromson).
- Name an owner for procurement questionnaires and build that work into the project plan (Dodd).
- Offer an implementation path that needs no engineering time from the carrier (Dodd).
- Map the stakeholders who hold influence and build relationships with several of them, not just one sponsor (Fromson).
- Cut any premium forecast for years one and two that you cannot defend line by line (Chekanava).
- Test whether an adviser would actually mention your product in a sale, and fix it if not (Fromson).
What will separate the insurtechs that scale over the next decade?
Each panellist gave a different answer. Chekanava backed founders who choose a niche problem and understand its ecosystem thoroughly, and who are driven by the mission as much as by revenue.
Identify the problem you are solving, stay focused and go deep.
For a capacity provider, depth signals longevity, because mission-driven founders stay when the tailwinds fade. Kaenprakhamroy looked at the market cycle instead. After roughly eight or nine years of hard conditions, she sees a softening market, mature technology and carriers ready for new products.
It's all going to be about distribution now.
Her argument is that the last decade rewarded technology and incremental product change, and that the next will reward whoever can reach customers. Fromson pointed to prevention, noting that claims costs are rising across life and health. Just as black boxes changed motor insurance, he expects AI-driven personalisation to help people avoid severe claims, for example keeping someone off long-term sick leave through income protection support.
Dodd focused on customers. Empathy's own research, she said, found that close to 100 per cent of Gen Z and 72 per cent of millennials expect bereavement care from their insurer. The winners, in her view, will operate where deep human emotion, complex operations and intense regulation meet, which is the claim rather than the purchase.
The most emotive moment in insurance is the claim, not the purchase, and the next generation of customers expects care at that point.
What this means for insurtech founders and the insurers who back them
- Founders raising capital: before accepting an offer, ask whether the investor has backed an insurance business through a year-long carrier cycle, and walk away if not.
- MGA founders seeking capacity: present a year one and two premium forecast conservative enough that a capacity provider would recognise it as realistic.
- Insurer innovation leads: give every insurtech partnership sponsors from several functions, so one departure does not reset the project.
- Heads of distribution at insurtechs: measure channels on cost over several years, and fund organic search and partner enablement before scaling paid acquisition.
Frequently asked questions
- How long does it take an insurtech to partner with a UK insurer? Panellists at ITC London put the typical timeline at 9 to 12 months, whether the project involves technology, capacity or a jointly built product. Iryna Chekanava of Chaucer said she had yet to see one close faster. Founders should plan their runway around that cycle rather than hope to shorten it.
- What do capacity providers look for in an insurtech or MGA? Chaucer's Iryna Chekanava said realism and honesty count for more than ambitious growth forecasts. An inflated addressable market or a large premium projection for the first two years is treated as a red flag. Capacity providers favour founders who pick a niche problem, understand it deeply and are driven by the mission.
- How should insurtech founders choose investors? Sam Fromson of YuLife advised treating every investor as a permanent partner, because removing a shareholder from the cap table is extremely difficult. The best investors understand insurance complexity and will support the long partnership cycle. Fit matters more than headline valuation.
- Which distribution channels work best for a UK insurtech? Tapoly's Janthana Kaenprakhamroy found organic search and long-nurtured partnerships outperformed paid advertising, which produced volume spikes but high costs. YuLife's experience shows that carrier channels work when advisers and sales teams actively champion the product. Either way, the product must add enough value to be mentioned at the point of sale.
Conclusion
The insurtechs that reach profit are rarely the ones with the boldest forecasts. The panel described businesses that planned for long carrier cycles, chose investors and capacity partners with care, and earned a place in the sales conversation.
Chekanava's view from the capacity side put it most sharply: a carrier that has watched every project take 9 to 12 months will back the founder whose forecast already admits it. To follow the sessions and speakers shaping the London Market, register your interest in ITC London 2027, or get in touch about partnership opportunities.
About our speakers
Clare Dodd
UK General Manager, Empathy
Dodd leads Empathy's UK business, which launched after the company scaled to more than 40 partnerships with insurers and banks in North America. She brings direct experience of carrier procurement and of designing support for customers in vulnerable circumstances.
Sam Fromson
COO and Co-Founder, YuLife
Fromson co-founded YuLife, which builds insurance products that reward healthier lifestyles and now works with close to a million individuals across the UK. He has built partnerships with major insurers and led international expansion into Japan and South Africa.
Janthana Kaenprakhamroy
CEO and Founder, Tapoly
Kaenprakhamroy founded Tapoly, a digital MGA platform serving the gig economy through wholesale and retail channels, nearly a decade ago. She previously worked in internal audit at an investment bank.
Iryna Chekanava
Senior Innovation Underwriter, Chaucer
Chekanava works in Chaucer's innovation team, part of the specialty insurer's underwriting division, where partnerships with insurtechs, MGAs and startups typically lead to capacity provision. She shared lessons from five years of the team's partnership work.
Finn Magee
CEO, Insurtech Canada
Finn Magee moderated this session.
Further reading
Based on a session delivered at ITC London 2026. Edited from the original transcript for clarity, structure and long-term reader value.
The next edition of ITC London is here. Registration for ITC London 2027 is now open. Secure your place, connect with the people shaping the industry, and be part of the conversation this time.